Credit, from application
to the last repayment.
Field file building, analysis, a reasoned decision signed at every level, disbursement, monitoring, collections and portfolio risk management: every role in your institution works in the same tool, and only sees what concerns them.
30-day free trial, no credit card. Then €440 per month (excl. VAT) for the whole institution.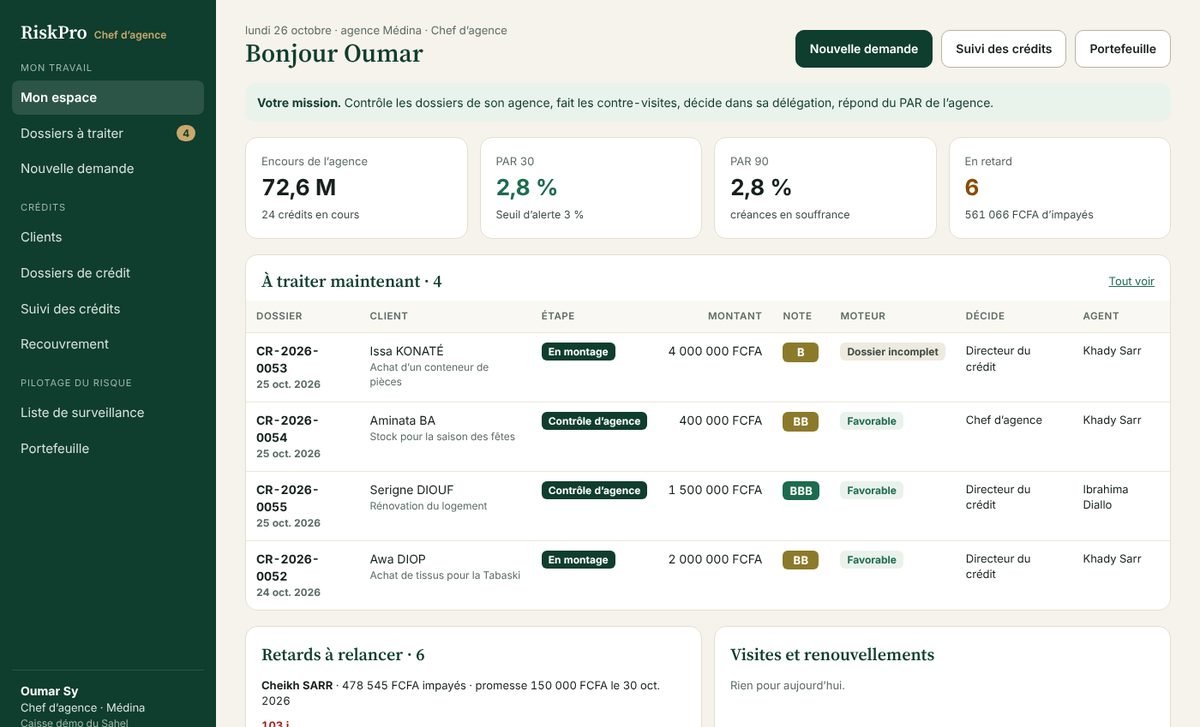
Everyone sees their modules. No one sees what is not theirs.
Rights are enforced by the server, not just hidden on screen. A loan officer only sees their clients, a branch manager only their branch. Role combinations that break segregation of duties are refused.
Their clients, applications, visits, arrears to chase and payment promises. On a phone, in the field.
Review and second visit, decisions within delegation, PAR of the branch and of each officer.
Credit bureau, financial analysis, scorecard, credit memo and reasoned opinion.
Independent opinion, watch list, provisions, IFRS 9, stress tests, limits.
Agenda, signed votes, quorum, minutes.
Conditions precedent, disbursement, repayment entry and import.
Loans past 90 days, legal action, four-eyes write-offs.
High-risk client approval, tamper-evident log, credit policy approved by the board.
An automatic, reasoned decision the loan officer can explain to the client.
- Knock-out rules: arrears in progress, regulatory single-borrower and group limits, usury rate.
- Repayment capacity by profile: salaried, informal business (microfinance method, weakest month), company (DSCR).
- Segment scorecards, probability of default, master scale from AAA to D.
- Favourable, with conditions or unfavourable, with the reasons, what would improve the file and a message ready to read to the client.
- Simulator: “what if we lend 1.5 M over 18 months?”
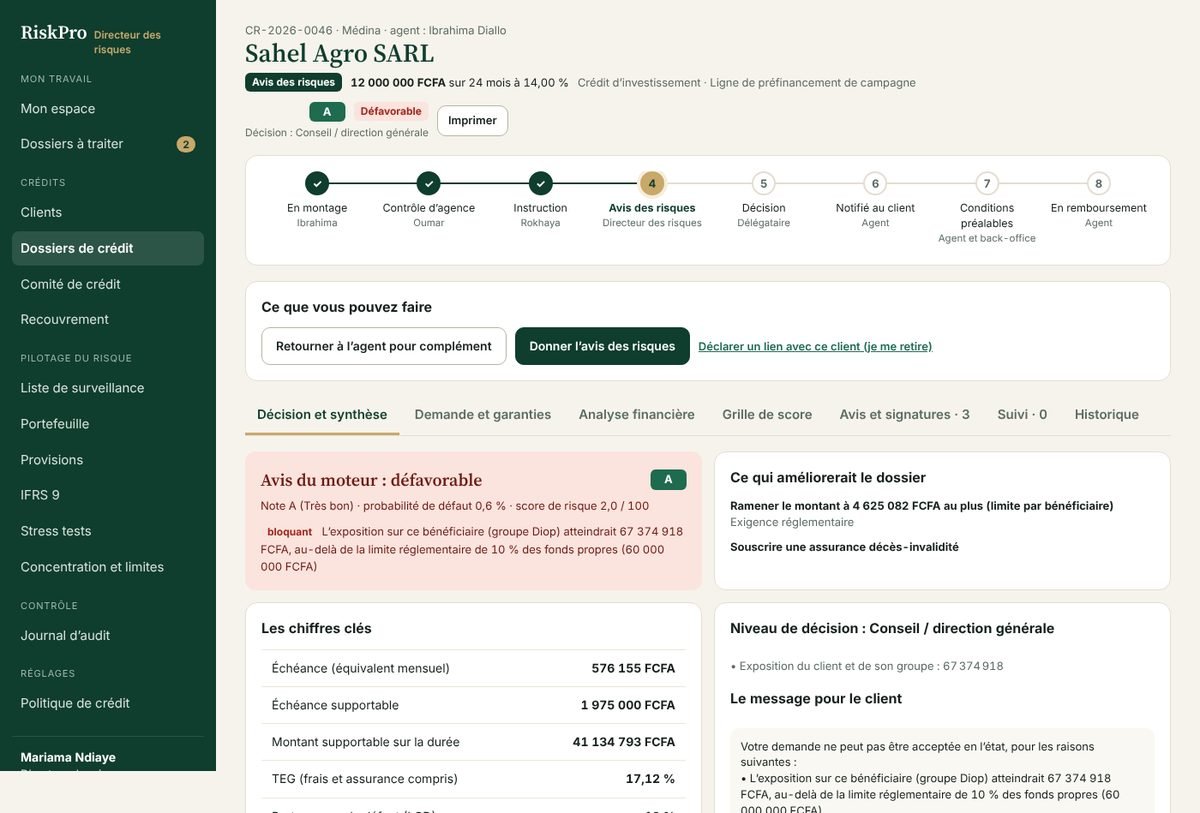
A visible trail for every file, and a signature at every step.
Every step is dated and signed. A signed opinion can no longer be changed: each signature carries the fingerprint of the previous one.
Delegations
The decision level is computed on the exposure of the client and their group, pending applications included: a loan cannot be split to slip under a delegation.
Segregation of duties
You do not decide a file you built. You do not disburse a loan you decided. You step aside from a file you have a link with.
Traced overrides
A decision against the engine’s opinion requires a written reason, visible to the chief risk officer and to audit.
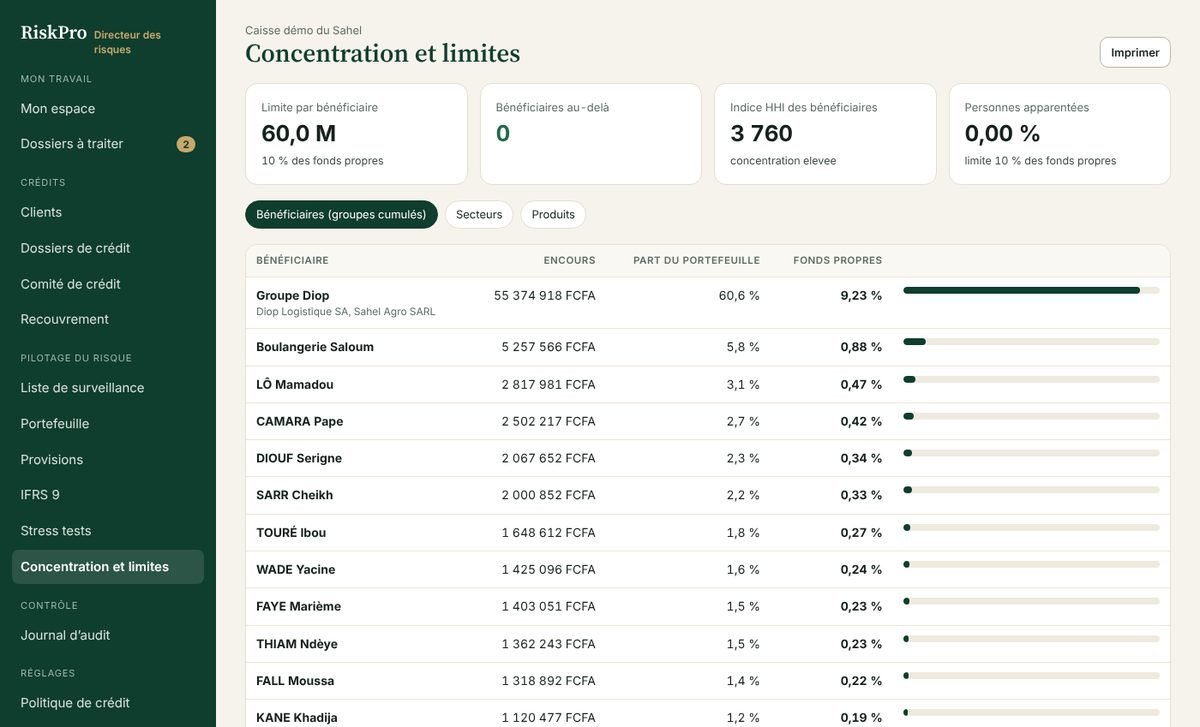
Management sees the risk, not just the outstanding balance.
- PAR 1, 30, 90 and 180 on outstanding principal, by branch and by loan officer.
- Provisions under your regulatory framework (WAEMU microfinance and banks, CEMAC, Morocco, Tunisia, DR Congo, EU), with contagion and eligible collateral.
- IFRS 9: stages, scenario-weighted, discounted expected credit losses.
- Stress tests, concentration by borrower, group, sector and product, related parties.
- Disbursement vintages and watch list.
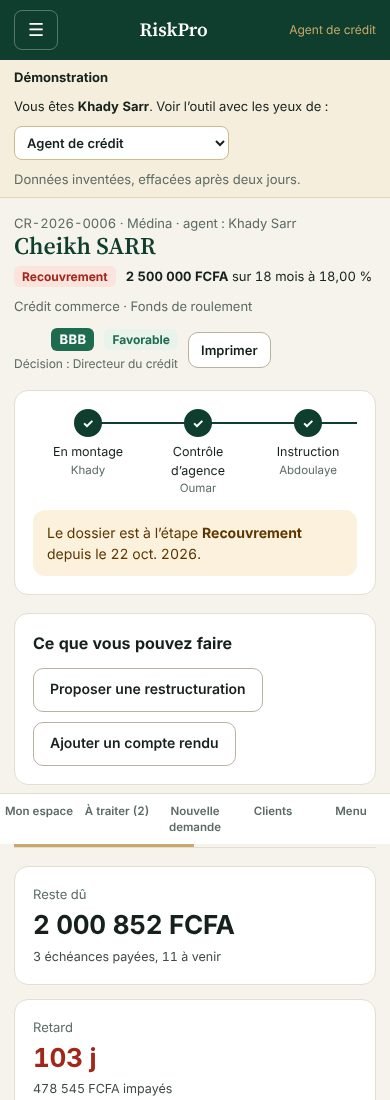
The loan officer carries the portfolio in their pocket.
The same tool on phone and computer: the client file, instalments, arrears, visit report and payment promise, entered in front of the client.
- Unlimited branches, users and files
- Every feature, every role
- Regulatory frameworks and updates
- Support by MAS_DATA Solution
- 30-day trial, no credit card, no commitment
Frequently asked questions
Are regulatory rates up to date?
Frameworks are provided for WAEMU, CEMAC, Morocco, Tunisia, DR Congo and the European Union. Each rate carries its source; those flagged “to verify” must be confirmed by the institution against the current text, and everything can be adjusted.
Who can change the credit policy?
The chief risk officer proposes it; the board or the CEO approves it. Nothing changes without both signatures.
Can we load our existing loans?
Yes. Repayments are imported from your core banking system (number, date, amount): arrears, PAR and provisions are recomputed at once.
Where is the data hosted?
In Europe (Frankfurt and Ireland), encrypted in transit. For WAEMU institutions, an in-zone backup can be arranged to meet regulation: let’s talk.
Is there an offline version?
Yes, RiskPro 2.1 runs without internet in a browser, with the same risk engine.
See the tool through the eyes of each role.
The demo is a fictitious microfinance institution: three branches, about sixty loans, one account per role.